Guide, 2 min read
Fixed Asset Tagging Checklist
Use this fixed asset tagging checklist to prepare staff, asset data, tag specifications, site access, verification and p…
 View Samples
How KRA wear-and-tear allowances depend on a verifiable asset register, and how physical asset tags support capital allowance claims and audits.



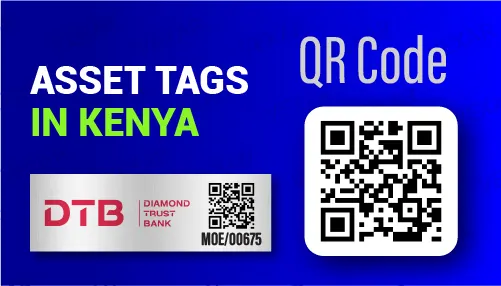
For CFOs, senior accountants and tax consultants, a fixed asset register is more than an accounting schedule. It provides an important record of the machinery, computers, vehicles, equipment and other assets owned and used by a business. When capital allowances are claimed, organisations need reliable records that support the underlying assets and expenditure.
This is where fixed asset tags businesses use can provide an important physical control.
A unique asset number, barcode or QR code connects an item on the factory floor, in a Nairobi office or at a regional project site to its corresponding fixed asset register entry. While an asset tag does not by itself establish eligibility for a tax deduction, it can make physical verification and reconciliation significantly easier.
Kenya’s current tax framework provides for investment allowances on qualifying capital expenditure. KRA publishes different rates depending on the category of asset, including machinery, motor vehicles, heavy earth-moving equipment, computers, furniture and telecommunications equipment.
A tax audit can require an organisation to demonstrate that its records accurately represent its business activities and assets.
Consider a manufacturing company that has claimed capital allowances on machinery acquired over several years.
Its accounting records may show:
But the physical asset still needs to be identifiable.
If the company has hundreds of machines, computers and pieces of equipment, relying only on descriptions and serial numbers can make reconciliation difficult.
A unique physical asset tag creates another layer of control.
For example:
| Asset Information | Example |
|---|---|
| Asset ID | MFG-MCH-00482 |
| Asset | Industrial packaging machine |
| Location | Nairobi production plant |
| Serial Number | Manufacturer serial number |
| Acquisition Date | Recorded in FAR |
| Tax Category | Recorded in tax schedule |
The tag allows the finance or audit team to locate the physical machine and compare it against the relevant accounting and tax records.
The terminology surrounding asset deductions can sometimes create confusion.
Older accounting and tax discussions frequently refer to “wear and tear allowances.” The current Kenyan framework uses the concept of investment allowance under the Second Schedule to the Income Tax Act.
KRA describes capital allowances as tax incentives available for qualifying capital expenditure and lists investment allowance rates for various categories of buildings and machinery.
The Income Tax Act also sets out the applicable treatment and rates for qualifying expenditure. The current legislation should always be checked when preparing a tax computation because tax rules and rates can change.
For businesses, the practical implication is straightforward: the tax computation needs to be supported by reliable underlying records.
That means the finance team should be able to trace an amount claimed in a tax computation back to the underlying asset, acquisition documentation and accounting records.
Physical tagging strengthens that traceability.
A fixed asset register exists in the accounting system.
The asset exists physically.
The challenge is proving that the two refer to the same item.
This is the gap that physical asset tagging helps bridge.
Consider the following workflow:
Purchase → Asset Registration → Asset Tagging → Asset Assignment → Physical Verification → Accounting Records → Tax Records
Each stage creates a connection between the transaction and the physical asset.
Without a unique identifier, two identical machines can easily be confused.
With fixed asset tags, each machine has its own identity.
This is particularly valuable for companies with:
One of the biggest problems during an asset review is a discrepancy between the fixed asset register and the physical assets.
For example, a company may have a machine recorded in its FAR, but the machine cannot be located during verification.
Several explanations are possible.
The machine could have:
Without a unique asset identifier, investigating the discrepancy becomes more difficult.
With a tag, the organisation can establish a clear history around the asset number.
This makes reconciliation more systematic and gives management better visibility before an external review or tax audit.
A strong fixed asset register audit should not focus solely on whether the spreadsheet balances.
The finance and audit teams should also consider whether the physical assets correspond with the records.
| Verification Area | Question to Ask |
|---|---|
| Asset existence | Does the physical asset exist? |
| Identification | Does its asset number match the FAR? |
| Serial number | Does the manufacturer serial number agree? |
| Location | Is the asset where the register says it is? |
| Custodian | Is the responsible department or employee correct? |
| Acquisition | Can the purchase be supported by documentation? |
| Condition | Is the asset operational, damaged or obsolete? |
| Tax treatment | Is the asset correctly classified? |
| Movement | Has any transfer been properly recorded? |
| Disposal | Has any disposed asset been removed appropriately? |
This process can identify discrepancies before they become larger accounting or tax-control problems.
A simple sequential number can be sufficient for basic asset identification.
However, organisations with hundreds or thousands of assets can benefit from machine-readable identification.
Barcode tags allow a scanner or compatible device to read the asset identifier quickly.
The process becomes:
Scan → Identify → Retrieve Record → Verify → Update
This reduces the amount of manual typing involved in a physical verification exercise.
For example, a finance team conducting an annual asset verification in a Nairobi office could scan the barcode on each computer, monitor or printer and compare the result against the organisation’s asset database.
The same principle can be applied to machinery at a manufacturing plant or equipment at a regional project site.
QR codes can take this process further by connecting the physical asset to a digital record.
Depending on the asset management system, scanning the QR code may provide access to information such as:
QR codes are particularly useful where employees already have smartphones or tablets available for asset verification.
However, the QR code itself does not create compliance.
It is simply the identification mechanism.
The organisation still needs accurate underlying records and appropriate financial and tax documentation.
Tax and financial audits can become more difficult when an organisation cannot quickly establish what its asset records represent physically.
A well-organised tagging system helps the finance team prepare before an audit.
The process can begin with a reconciliation exercise:
Obtain the latest FAR from the accounting system.
Separate assets by branch, office, factory, warehouse or project site.
Locate each asset and confirm its condition and location.
Confirm that the physical identification number matches the FAR.
Investigate missing, transferred, disposed or incorrectly recorded assets.
Confirm that acquisition records, invoices and other relevant documentation are available.
Correct the FAR and related schedules before the audit.
This approach gives management a better understanding of its records before responding to questions from auditors or tax authorities.
Capital allowance calculations depend on the proper treatment of qualifying capital expenditure.
KRA’s published guidance identifies different investment allowance rates for categories such as manufacturing machinery, motor vehicles and heavy earth-moving equipment, computer hardware and software, furniture and fittings, telecommunications equipment and other machinery.
The tax treatment therefore depends on what the asset is and how it is classified.
Physical identification helps finance teams maintain consistency between the asset, its accounting classification and the tax schedule.
For example, if a company owns 100 computers, each computer can be assigned a unique identifier.
The finance team can then reconcile:
Purchase documentation → FAR → Physical asset → Asset tag → Tax schedule
This does not replace professional tax analysis or supporting documentation.
It simply creates a stronger audit trail.
The absence of an asset tag should not automatically be presented as a standalone reason why a legitimate tax claim would be disallowed.
Tax deductibility and capital allowance eligibility depend on the applicable provisions of Kenyan tax law and the evidence supporting the claim.
However, poor physical asset identification can make it more difficult for a taxpayer to demonstrate that assets recorded in its accounts and tax schedules exist, are correctly identified and are used as claimed.
That distinction is important.
Asset tagging is an internal control and verification tool.
It is not a substitute for invoices, purchase agreements, accounting records, tax schedules or other required documentation.
For CFOs and tax consultants, the objective should therefore be to build an evidence chain that is consistent from acquisition through accounting, physical custody and tax reporting.
Not every asset requires the same tag material.
A laptop in a controlled Nairobi office has different requirements from a generator at a construction site.
| Asset Type | Recommended Tag | Reason |
|---|---|---|
| Office computers | Barcode or QR vinyl/polycarbonate | Indoor environment |
| Servers | Durable barcode or QR tag | Long-term IT identification |
| Factory machinery | Anodized aluminium | Industrial exposure |
| Generators | Aluminium asset tag | Heat, dust and outdoor exposure |
| Construction equipment | Heavy-duty aluminium | Abrasion and site conditions |
| Fleet vehicles | Aluminium or durable industrial tag | Outdoor exposure |
| Agricultural machinery | Anodized aluminium | Dust, moisture and chemicals |
| Warehouse equipment | Barcode/RFID | High-volume identification |
For industrial assets, anodized aluminium can offer better long-term performance than ordinary vinyl because it can withstand demanding conditions more effectively.
Kenyan businesses operating outside controlled office environments may expose asset tags to harsh conditions.
A generator at a construction site can encounter dust, oil, heat and physical abrasion.
Agricultural machinery can encounter fertilizers, moisture and soil.
Solar installations can experience prolonged UV exposure.
Equipment transported along major logistics routes can also experience repeated handling and movement between sites.
For these applications, anodized aluminium can provide a durable surface for asset identification.
The complete tag specification still matters, including the adhesive and marking technology.
A strong metal face does not guarantee performance if the adhesive is unsuitable for the surface or environment.
For organisations reporting under IFRS, physical asset identification can also support broader financial reporting controls.
Accounting standards require organisations to maintain appropriate information about assets, including matters relevant to recognition, measurement, depreciation and impairment.
An asset tag does not create IFRS compliance by itself.
However, it can support the underlying asset-management process by helping finance teams identify individual assets and reconcile physical records with accounting records.
This is particularly relevant where a company has a large property, plant and equipment portfolio.
The finance department can use asset identifiers to support processes such as:
For organisations operating across Nairobi and other locations, a consistent identification system can make these processes easier to manage.
A formal asset tagging policy can establish consistency across the organisation.
It should define:
Determine how unique asset numbers will be generated.
Specify whether tags will contain numbers, barcodes, QR codes or RFID.
Define when vinyl, polycarbonate or aluminium should be used.
Specify where tags should be attached to different asset categories.
Define who creates, applies and verifies tags.
Establish how asset movements should be recorded.
Define how often physical verification should take place.
Ensure tags and asset records are addressed when assets are disposed of.
A written policy reduces the risk of different departments adopting inconsistent tagging practices.
Several mistakes can undermine an otherwise effective system.
The physical tag and accounting record must correspond.
Every asset should have a unique identifier.
A low-cost office label may not survive a factory, farm or construction environment.
Moving equipment without updating the records creates location discrepancies.
Replacement or removal during maintenance should be documented.
An asset register should not be assumed to remain accurate indefinitely.
The tag supports identification. It does not replace invoices, accounting records or tax evidence.
A practical pre-audit review can identify problems before an external auditor or tax authority raises them.
Start by extracting the latest FAR.
Then compare the register against the physical assets.
Mark each item as:
Investigate every exception.
If an asset is recorded but cannot be found, determine what happened to it.
If an asset exists physically but is absent from the register, investigate whether it was recently acquired, transferred or incorrectly recorded.
This exercise can reveal weaknesses in asset management that extend beyond tax.
For a CFO, the value of asset tagging should not be measured only by the cost of the labels.
The bigger question is what the organisation gains from accurate physical identification.
A well-designed system can help:
For organisations with significant capital expenditure, these benefits can outweigh the relatively small cost of the tags.
Capital allowances are an important part of the Kenyan tax framework, but the underlying asset records need to be accurate and defensible.
KRA’s published guidance confirms that qualifying capital expenditure can attract investment allowances at specified rates depending on the type of asset.
For finance teams, the practical objective is therefore to maintain a clear chain of evidence.
The asset should be identifiable.
The acquisition should be documented.
The asset should be correctly recorded in the FAR.
The physical asset should be capable of being verified.
The relevant tax treatment should be supported by the applicable tax rules and records.
Fixed asset tags businesses use can help connect these different layers.
They do not replace tax compliance, professional accounting judgement or statutory documentation.
They make physical identification more reliable.
If your organisation is preparing for a fixed asset register audit, reviewing its capital allowance records or improving internal asset controls, physical asset tagging can provide a practical foundation for better verification.
Choose the tag according to the asset and its environment. Use barcode or QR identification where digital scanning is useful, and consider durable anodized aluminium for machinery, vehicles and outdoor equipment exposed to demanding conditions.
Request a quote or order a free sample pack of fixed asset tags in Kenya and test the material, adhesive, numbering and barcode or QR readability before rolling out your tagging programme.
A stronger asset register begins with knowing exactly which physical asset each record represents.
Prev Previous Lifecycle of Aluminium Asset Tags: Manufacturing to Deployment Next Acetone-Activated vs. Riveted Aluminium Asset Tags: Which Installation Method is Best? NextBranded Mousepads, Product Stickers & Labels , Reflector Jackets , Roll-Up Banners, Sellotapes Branding, Staff ID Cards, Wheel Covers Branding, Presentation Folders, Letterhead Printing, Diaries Printing, Vehicle Branding, Jerseys Printing, Booklets Printing, Posters Printing, Leaflets Printing, Brochure Printing, Flyers Printing, Notebook Printing, Spiral Bound Booklet, Reflective Stickers, Pop-up Banners, Umbrella Branding, Book Printing, Metallic Door Signs, 3D LED Signs, Asset Tags, Bookmarks Printing, Custom Tapes, Telescopic Banners, Mounted Photos, Floor Stickers, Business Cards, Custom Posters, Calendar Printing, Water Bottles Mugs Branding Envelopes Printing Tear-Drop Banner Backdrop Banner Funeral Programs Feather Flags Certificate Printing Polo Shirts Trophies & Awards Spiral Notebooks Annual Reports Plaques Staff Nametags Branded Keyholders Snapper Frames Stationery Giveaways Button Badges Fridge Magnets Laptop Bags Samples Laser Asset Tagging
Claims should be supported by a register of real, identifiable assets. Tags make it easy to prove that claimed assets exist.
Purchase invoices, the fixed asset register with tag numbers, locations and dates, and disposal records.
No. This guide explains good record-keeping. Confirm tax treatment with your accountant or tax adviser.
Written by the Vexar Solutions team
We have made aluminium asset tags and carried out asset tagging for Kenyan organisations since 2016. About us.
Guide, 2 min read
Use this fixed asset tagging checklist to prepare staff, asset data, tag specifications, site access, verification and p…
Guide, 12 min read
A practical fixed asset verification and tagging guide for SMEs: counting, tagging, building the register and keeping it…
Guide, 5 min read
The 5 fixed asset tag types most used in Kenya, compared: aluminium, barcode, QR, polyester and tamper-proof, with the a…
Need asset tags or printing in Kenya?
Send your quantity and artwork. We reply with a quote and a free proof, usually within the hour.